Buy now, pay later: Convenient or costly?
 Print
 Email
Small payments can make a purchase feel affordable—but what will it cost your future budget?
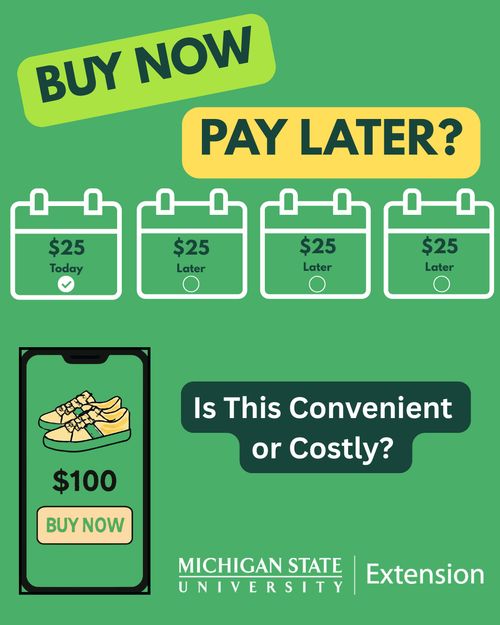
You spot something you want online. The price is $100, but instead of paying $100 today, you only need to pay $25. The remaining three payments will come later. Sounds affordable, right?
That is exactly why Buy Now, Pay Later (BNPL) services have become so popular. BNPL allows consumers to immediately own or access a good or service while spreading out the cost over an agreed timeframe. Plus, these short-term loans often do not charge interest if payments are made on time.
For many people, BNPL can be a helpful tool. It can make it easier to manage a limited income, handle an unexpected expense, or spread a larger purchase across multiple paychecks. However, it is important to remember one thing: Paying later does not mean paying less.
According to the Federal Reserve's 2025 Survey of Household Economics and Decision-making, 16% of adults reported using a BNPL service in 2025. Usage is higher for women, younger adults, adults without bachelor’s degrees and Black and Hispanic adults. Usage was especially common among young adults ages 18-29, with 22% saying they had used BNPL.
While BNPL can make purchases feel more manageable, the payments can still create challenges. The survey found that 32% of BNPL users aged 18-29 reported making at least one late payment. Among users with household incomes below $25,000, that number increased to 40%.
Missing a payment can have consequences. Depending on the provider, consumers may face late fees, account restrictions or other penalties. According to the Federal Reserve’s August 2026 issue of Consumer & Community, overall, 21% of BNPL users reported being charged extra for paying late or incurred an overdraft or non-sufficient funds (NSF) fee from their bank.
What to know before you click "Buy Now"
Weighing whether BNPL is right for you? Take a moment to ask yourself these questions:
Can I afford the entire purchase, not just today's payment?
The first payment may seem small, but you are agreeing to pay the full amount. Review your upcoming bills, expenses and financial commitments before adding another payment to your budget.
How many BNPL payments am I already making?
Several small payments can quickly add up. What feels affordable today may become difficult when multiple payments are due at the same time, competing with essentials like rent, groceries, transportation or utilities.
What happens if I miss a payment?
Read the terms carefully before making a purchase. Understand the repayment schedule, automatic withdrawal policies, potential fees and any penalties for late payments. Michigan State University Extension recommends understanding all repayment requirements before using BNPL services.
BNPL is not automatically a bad financial choice. When used responsibly, it can be a convenient way to manage expenses. However, every BNPL purchase is a commitment of future income.
Before you click "Buy Now," ask yourself whether your future budget can comfortably handle those upcoming payments. A purchase should fit your budget not only today, but also in the weeks ahead.
MSU Extension and Michigan 4-H Youth Development help to prepare young people for successful futures. To find out how to get involved as a Michigan 4-H youth participant or an adult volunteer, contact your county MSU Extension office.
Find more information about financial management and housing, visit MSU Extension’s MIMoneyHealth.org.